Switching the Death Benefit Option in IUL
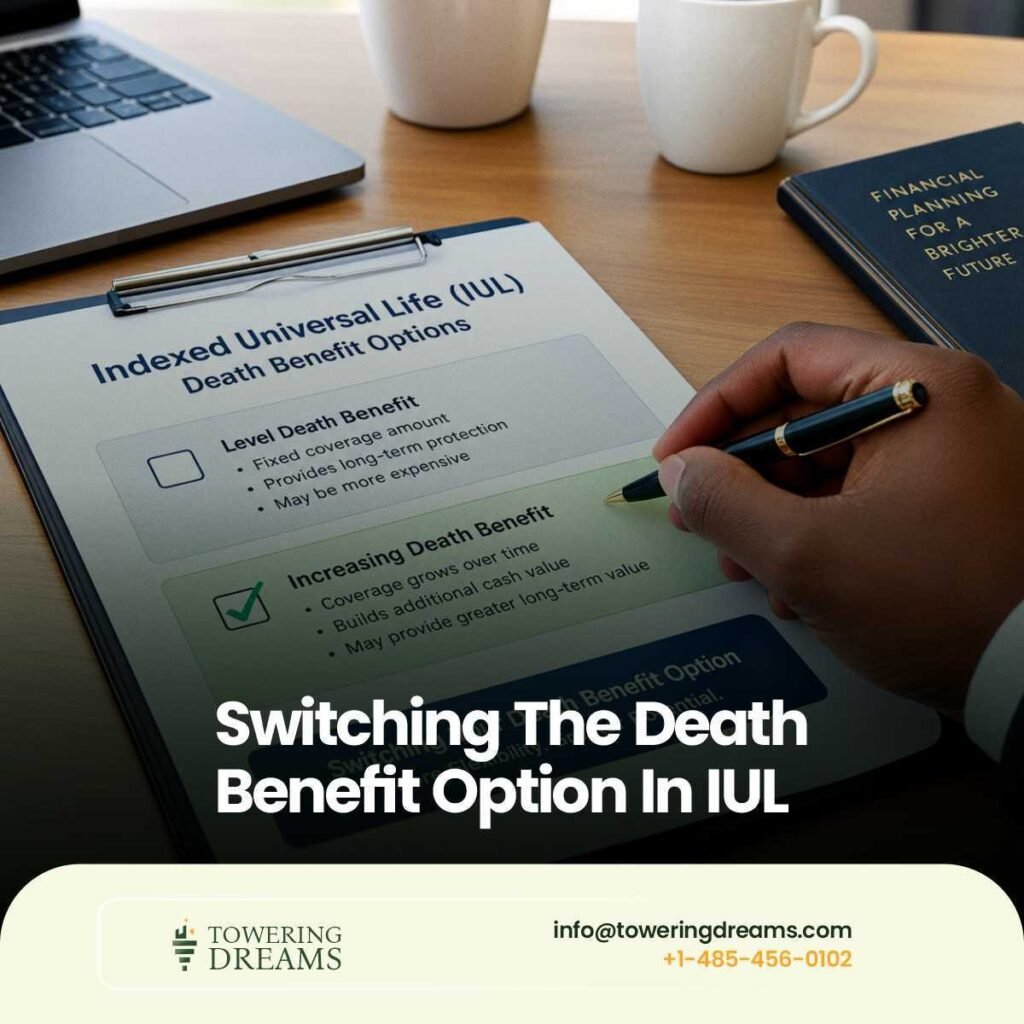
One of the lesser-known features of an indexed universal life policy is the ability to choose, and later switch, between different death benefit structures without necessarily starting a brand new policy from scratch. This flexibility is built directly into the design of most IUL contracts, and it exists precisely because the right death benefit structure […]
Can I Update My IUL Policy?
Life does not stay still, and neither do the circumstances that led someone to buy an indexed universal life policy in the first place. A policy purchased at 35 to cover a mortgage and young children looks very different from the coverage that same person might need at 55, once the mortgage is paid down, […]
What Is an Assumed Interest Rate in IUL?
Every indexed universal life illustration includes a number that quietly does more work than almost any other figure on the page: the assumed interest rate. It is the rate used to project how a policy’s cash value will grow over the years shown in the illustration, and it directly shapes how impressive or modest the […]
What Is a Stress Test in IUL?
An indexed universal life illustration showing steady, attractive growth year after year can be reassuring, but it can also be quietly misleading. Real markets do not move in smooth, consistent lines. They rise, fall, stagnate, and occasionally do all three within the same decade. A stress test is the tool used to answer a question […]
Case Modeling for an IUL Policy
Buying an indexed universal life policy without running a proper case model is a bit like signing a mortgage without ever looking at an amortization schedule. The policy might be structured well, priced fairly, and issued by a reputable carrier, yet without a clear picture of how premiums, charges, and crediting assumptions interact over decades, […]
Market Volatility in IUL
Market volatility is one of the first things people worry about when they hear “the stock market” and “life insurance” in the same sentence. Most of us have watched our 401(k) balances swing wildly during a downturn, and tying a life insurance policy to market performance can sound like inviting that same stress into a […]
IUL As A Risk-Management Tool
Indexed Universal Life insurance is most commonly discussed as a wealth accumulation and retirement income tool — a vehicle for building tax-advantaged cash value and generating tax-free income in later life. This framing is accurate and important. But it captures only part of what IUL can do. At its foundation, IUL is a risk management […]
Can I Modify My IUL Policy?
An Indexed Universal Life policy is sold with the understanding that life will not stay still. The insured changes jobs, income rises and falls, children are born, a business is sold, health changes. A policy designed for one stage of life will rarely fit the next, and the question of what can be changed, at […]
Optimizing The Long-Term Performance Of An IUL Policy
Purchasing an Indexed Universal Life insurance policy is the beginning of a long-term financial relationship, not a one-time transaction. The policy you design today will need to perform reliably for decades, adapting to changes in your income, your family structure, market conditions, and tax law. Yet many policyholders treat their IUL policy like a set-and-forget […]
What Is A Spread In IUL?
When evaluating an Indexed Universal Life insurance policy, most policyholders and advisors focus on two numbers: the cap rate and the floor. The cap is the maximum index credit the policy can earn in a given year; the floor — usually 0% — is the minimum. These two parameters define the range of possible outcomes […]