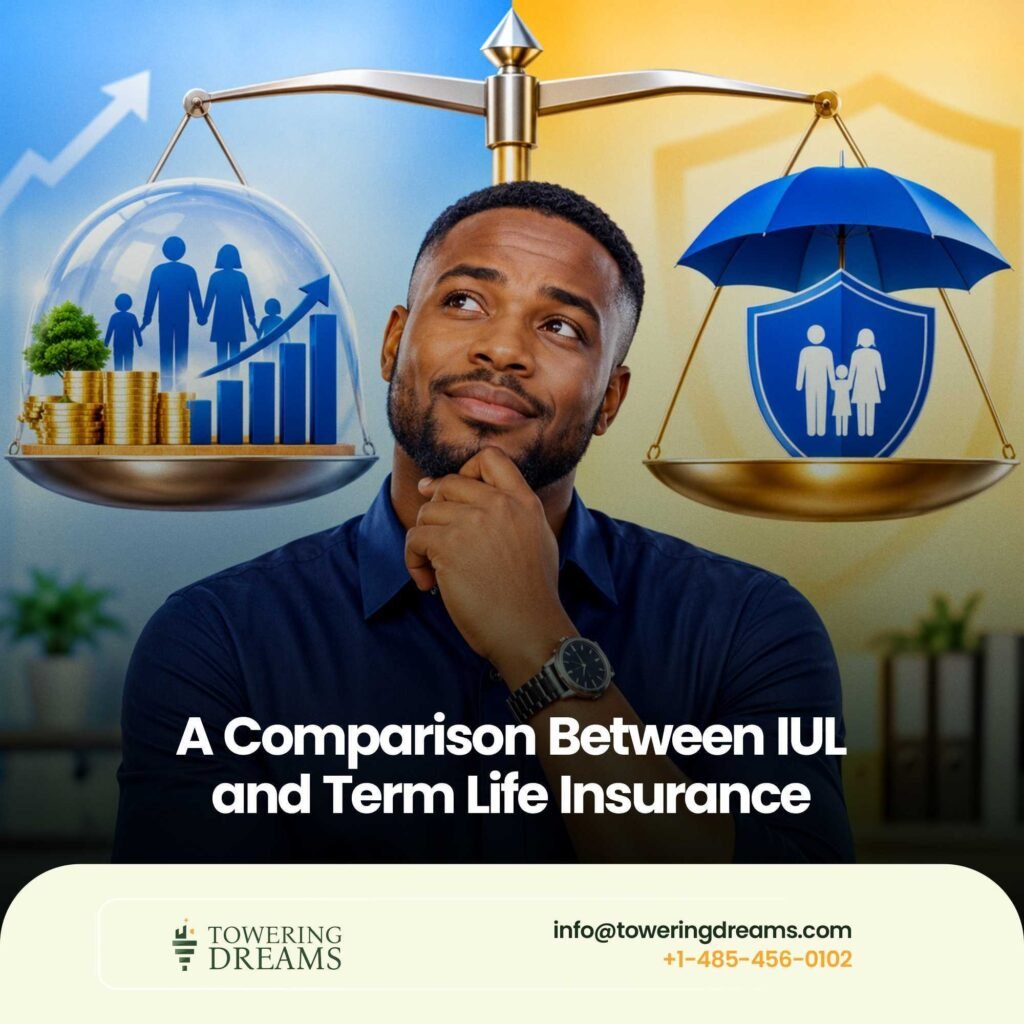
When people shop for life insurance, they quickly run into two very different options. Term life insurance offers straightforward protection for a set number of years at a relatively low cost. Indexed universal life, or IUL, offers lifelong coverage along with a cash value account that can grow based on the performance of a market index. Both can be valuable, but they are built for different purposes.
Because the two are priced and structured so differently, comparing them is not simply a matter of picking the cheaper one. The right choice depends on how long you need coverage, what you want the policy to accomplish, how much you can afford and how comfortable you are with complexity.
This article compares IUL and term life insurance across cost, duration, cash value, risk and flexibility, and explains how to decide which one fits your situation, or whether a combination makes sense.
Summary
Term life insurance provides a death benefit for a fixed period, such as ten, twenty or thirty years, and has no cash value. It is typically the most affordable way to obtain a large amount of coverage, which makes it well suited to temporary needs like a mortgage, raising children or replacing income during working years.
IUL is permanent insurance that can last for life if properly funded. It includes a cash value component linked to an index, with a floor that limits losses and a cap that limits gains. It costs considerably more than term and is more complex, but it offers lifelong coverage, tax-advantaged accumulation and flexibility. Many people use term for core protection and consider IUL only when they have a long-term need and the means to fund it consistently.
What Is Term Life Insurance?
Term life insurance is the simplest form of life insurance. You choose a coverage amount and a term, pay a premium, and if you die during that term, your beneficiaries receive the death benefit. If you outlive the term, the policy ends and no benefit is paid, unless you have added a rider such as return of premium.
Premiums are generally level for the length of the term, so a thirty-year policy keeps the same payment for thirty years. Because the policy does not build cash value and is not designed to last for life, the cost is much lower than permanent insurance for the same death benefit.
Many term policies include a conversion option, which allows you to convert to a permanent policy without a new medical exam, usually within a stated period. Some also allow renewal after the term ends, although premiums typically rise sharply at that point. Term is widely used by families and individuals who want a dependable safety net during the years when others rely on their income.
What Is an IUL Policy?
Indexed Universal Life (IUL) Insurance is a type of permanent life insurance. It pays a death benefit whenever the insured passes away, provided the policy remains in force. A portion of each premium goes to pay the cost of insurance and policy charges, and the rest goes into a cash value account.
The cash value is credited with interest based on the performance of a market index, such as the S&P 500. The policy owner does not invest directly in the index. Instead, the insurer uses it as a reference. If the index rises, the credited interest is limited by a cap, participation rate or spread. If the index falls, the credited rate is typically floored at zero.
IUL premiums are flexible within limits, and the death benefit may be adjustable. The owner may also borrow against or withdraw from the cash value. This combination of coverage, accumulation and access is the main appeal, but it also introduces costs, variables and risks that term insurance does not have.
Comparing Cost and Premiums
Cost is the most obvious difference. For the same death benefit, term insurance is usually far cheaper than IUL, often by a wide margin, especially for younger and healthier buyers. That is because term only covers the risk of death during a limited period, while IUL must support lifelong coverage and a cash value component.
IUL premiums are not just insurance costs. A significant portion may be directed to the cash value, and the policy also carries administrative charges, cost of insurance deductions that rise with age and sometimes surrender charges in the early years. Premiums may be flexible, but if they are too low the policy can lapse.
For someone with a limited budget, the cost gap can be decisive. The same monthly amount that buys a modest IUL might purchase a much larger term policy, providing far more protection for dependents. Protection should usually come first, and a policy that is too expensive to maintain can end up providing no benefit at all.
Comparing Duration and Coverage
Term insurance covers a defined period. If the need extends past the term, you must renew at higher rates, convert to a permanent policy or buy new coverage, which may be costly or impossible if your health has declined. This is not a flaw, since many needs are temporary, but it is a limitation.
IUL is designed to last for life if it is adequately funded. This makes it suitable for permanent needs such as estate liquidity, leaving a legacy, final expenses or providing for a dependent with lifelong needs. The death benefit does not expire at a set date.
However, lifelong coverage is not automatic. An IUL needs enough funding to cover rising insurance costs in later years. If credited returns fall short of the illustration or premiums are reduced, the policy can lapse. By contrast, a term policy with fixed premiums is simple to maintain throughout its term.
Comparing Cash Value, Tax Treatment and Living Benefits
Term insurance has no cash value. All premiums go toward the cost of coverage, and there is nothing to borrow against or withdraw. The benefit is paid only on death within the term, though some policies include accelerated death benefit riders for terminal illness.
IUL builds cash value that can be accessed through withdrawals or policy loans. Under current U.S. tax law, the cash value generally grows tax-deferred, and loans and withdrawals up to basis are generally not taxed, provided the policy remains in force and is not a modified endowment contract. The death benefit is generally income tax-free to beneficiaries for both products.
Many IULs also offer riders that provide access to part of the death benefit for chronic or terminal illness. These features can add value, but they are not free. The tax benefits also depend on the policy being structured and maintained correctly, so professional guidance is advisable before relying on them.
Comparing Risk, Complexity and Flexibility
Term is easy to understand. You know the premium, the death benefit and the length of coverage. There are no caps, participation rates, crediting methods or index options to evaluate, and there is little uncertainty about how the policy will perform.
IUL is more complex. Its performance depends on caps, participation rates, spreads, crediting methods and the index chosen. Most of these terms are not guaranteed beyond contractual minimums and can be changed by the insurer. Illustrations show projections based on assumptions, and some are optimistic. Understanding these elements takes effort, and buyers should ask to see conservative scenarios and guaranteed values.
On the other hand, IUL offers flexibility that term does not. Premiums can often be adjusted, cash value can be accessed and the policy can be tailored with different index strategies. The right level of complexity depends on whether you value that flexibility enough to accept the added risk of mismanagement or underfunding.
How to Choose Between IUL and Term
Begin with your needs. If your main goal is to protect your family during a specific period, such as until the children are grown or the mortgage is paid, term is usually the most efficient solution. If you need coverage that lasts for life, or want a tax-advantaged cash value component after maximizing other savings options, IUL may deserve a look.
Consider your budget and discipline. A policy that is difficult to afford can lapse, and an IUL requires consistent funding and regular reviews. If you are unsure, buying adequate term coverage first is generally safer than overextending on a permanent policy.
Many people combine the two. A common approach is to hold a large term policy to cover the highest-need years and a smaller permanent policy for lifelong needs. Some also buy term and invest the difference elsewhere, such as in retirement accounts. A licensed professional can model these options, compare quotes from several insurers and help you decide which approach fits your goals.
You can always book a free strategy session with us. We will be glad to help you set up a policy and to help you make the most of it to achieve your aims and objectives.
Conclusion
Term life insurance and IUL serve different purposes. Term offers low-cost, simple protection for a limited time, while IUL offers lifelong coverage with a cash value component, at a higher cost and with more complexity and risk.
Neither is best for everyone. The better choice is the one that matches your needs, your budget and your ability to maintain the policy. Start with the protection your family needs, be realistic about the costs and assumptions, and review your coverage as your life changes.
Indexed Universal Life Insurance(IUL) policies have a lot of features that can potentially provide a safety net for you and for your loved ones. You should check out this video on how to safeguard your future and that of your loved ones against unforseen circumstances like job loss or illnesses for more information.
FAQ
Question 1: Which is cheaper, IUL or term life insurance?
Answer: Term life insurance is generally much cheaper than IUL for the same death benefit. It provides coverage only for a set period and does not build cash value, while IUL is designed to last for life and includes a cash value component.
Question 2: Does term life insurance have cash value?
Answer: No. Term insurance has no cash value, so if you outlive the policy, you do not receive a payout, unless you purchased a return of premium rider. Its low cost reflects the fact that it only provides a death benefit during the term.
Question 3: Is IUL a good investment?
Answer: An IUL is primarily a life insurance product, not a pure investment. Its cash value growth is limited by caps and participation rates, and its costs can be high. It may complement other savings, but it should not replace retirement accounts or other investments.
Question 4: Can I convert a term policy to an IUL?
Answer: Many term policies include a conversion option that allows you to convert to a permanent policy without a medical exam, within a set period. The permanent options available for conversion vary by insurer, so you should check your contract to see whether an IUL is included.
Question 5: Can I own both IUL and term life insurance?
Answer: Yes. Many people use term for large, temporary needs such as income replacement and a mortgage, and a smaller permanent policy for lifelong needs. A professional can help determine the right balance for your situation.
At Towering Dreams we help American families to choose the right type of Indexed Universal Life ( IUL ) & Annuity plan.